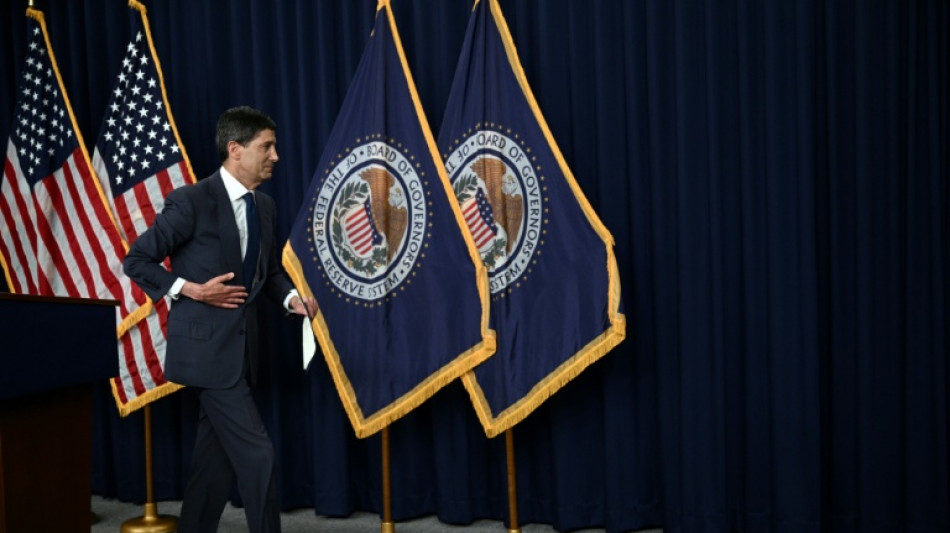
Lofty bond yields, Bessent's intervention pose challenge to Fed's Warsh / Photo: Brendan SMIALOWSKI - AFP/File
US Treasury Secretary Scott Bessent's controversial efforts to lower Treasury yields have potentially put him at odds with Federal Reserve Chair Kevin Warsh, complicating the latter's communications challenge this week.
Warsh will deliver the opening address at the annual central bankers conference in Jackson Hole, Wyoming, on Friday, and will be expected to address recent Treasury interventions in the bond market.
The new Fed chair has faced criticism over sending sometimes confusing signals at press conferences in his tenure so far, including on how he sees bond yields.
In June, Warsh said he was comfortable with lower bond yields, but six weeks later said higher bond yields were actually doing some of the Fed's financial tightening for them.
Last week, however, the Treasury Department announced that it planned to "at least double" its purchase of longer-dated bonds.
The policy came a day after 30-year US Treasury bond yields reached their highest level since 2007. Bessent said he saw the bond yields as not reflective of market realities.
The Treasury secretary, a savvy practitioner in markets with decades of experience in finance, has had "very mixed success" with the effort to lower yields, said Ehud Ronn, a finance professor at the University of Texas at Austin.
Yields remain high by modern historical benchmarks, with some observers viewing any moderation as resting more on the course of oil prices than future Treasury interventions.
"This policy, far from reducing uncertainty, has added to it," said Richard Berner, co-director of the Stern Volatility and Risk Institute at New York University.
Stanley Druckenmiller, a billionaire investor who is considered a mentor to both Bessent and Warsh, blasted the policy in a Wall Street Journal op-ed earlier this week.
"Markets aggregate information no committee possesses, and prices are how that information reaches decision makers," Druckenmiller wrote.
"Every basis point of artificial yield suppression is a subsidy to procrastination," he said.
"Suppressed long rates sugarcoat the interest-cost projections, shrink the apparent urgency, and let incumbents assure voters the debt is someone else's problem."
Analysts also see efforts to push yields lower as running counter to moves to contain inflation after US President Donald Trump's war on Iran pushed oil prices sharply higher.
Higher interest rates, whether dictated by the Fed or bond markets, can limit a cycle of economic overheating in which prices spiral further out of control.
- Response to inflation? -
The Fed has not hiked interest rates since December 2025. But markets reacted poorly to Warsh's last news conference, where he touted the "impressive resilience" while delivering an ambiguous message about what the central bank would do to counter inflation.
While Warsh insisted the Fed would achieve price stability, he and other policymakers decided against raising interest rates, the central bank's most obvious tool for countering inflation.
"Jackson Hole gives Kevin Warsh an opportunity to restore the inflation-fighting credibility that Scott Bessent's debt management strategy cannot provide on its own," said Stephen Innes, head of trading at SPI Asset Management.
But not everyone is expecting to learn much this week about Warsh's plans.
"A lot of people will be listening to Kevin Warsh, but I think those people will be disappointed by what he does not say because I think he wants to keep his cards close to his vest," said Sam Stovall of CFRA Research.
Under Warsh, the Fed has pared back its official monetary policy announcements and the new chair has spoken of his desire for the markets to respond to financial conditions rather than the views of central bankers.
But markets have been uncomfortable with this approach.
"It's even more important that people understand what the Fed is doing and why they're doing it," Berner said. "The market participants and policymakers and people like me are asking him to be more forthcoming about what he's doing."
P.Benes--TPP