The Prague Post - Venezuela and the Qatar Fund

EUR -
AED 4.126854
AFN 73.041992
ALL 91.264799
AMD 406.843082
ANG 2.011211
AOA 1030.448522
ARS 1702.716467
AUD 1.613608
AWG 2.024095
AZN 1.914779
BAM 1.955046
BBD 2.266626
BDT 138.436605
BGN 1.964067
BHD 0.425636
BIF 3368.300856
BMD 1.123717
BND 1.439645
BOB 13.138932
BRL 5.691742
BSD 1.125366
BTN 106.809804
BWP 15.418053
BYN 3.388993
BYR 22024.845083
BZD 2.263427
CAD 1.590902
CDF 2599.722726
CHF 0.928113
CLF 0.027959
CLP 1100.405577
CNY 7.519017
CNH 7.51396
COP 3566.624364
CRC 511.402753
CUC 1.123717
CUP 27.009582
CVE 110.222488
CZK 24.323187
DJF 200.402705
DKK 7.474068
DOP 69.033374
DZD 150.380998
EGP 60.152199
ERN 16.855749
ETB 183.8243
FJD 2.548196
FKP 0.843011
GBP 0.845122
GEL 2.910865
GGP 0.843011
GHS 13.141931
GIP 0.843011
GMD 82.597496
GNF 9900.18153
GTQ 8.598684
GYD 235.449188
HKD 8.819097
HNL 30.211348
HRK 7.533176
HTG 147.373159
HUF 363.309245
IDR 20286.455525
ILS 3.47751
IMP 0.843011
INR 106.714312
IQD 1706.041985
IRR 2018057.337243
ISK 136.172409
JEP 0.843011
JMD 178.891002
JOD 0.79676
JPY 177.564121
KES 146.193614
KGS 98.269447
KHR 4574.235731
KMF 494.435691
KPW 1011.344884
KRW 1499.869907
KWD 0.349274
KYD 0.937838
KZT 509.263579
LAK 25322.23329
LBP 100778.729946
LKR 372.726241
LRD 191.875994
LSL 18.499065
LTL 3.318043
LVL 0.679725
LYD 7.227212
MAD 10.933383
MDL 20.189213
MGA 5065.046427
MKD 61.621233
MMK 2359.646377
MNT 4042.305032
MOP 9.097991
MRU 44.990647
MUR 53.07356
MVR 17.373083
MWK 1951.447333
MXN 20.780783
MYR 4.588364
MZN 71.80968
NAD 18.499065
NGN 1495.90318
NIO 41.414027
NOK 10.594067
NPR 170.896086
NZD 1.985892
OMR 0.429724
PAB 1.125366
PEN 3.871007
PGK 5.110029
PHP 70.778456
PKR 311.536341
PLN 4.369291
PYG 6427.520924
QAR 4.113613
RON 5.315858
RSD 117.384725
RUB 94.543535
RWF 1661.059334
SAR 4.217125
SBD 9.062378
SCR 15.625873
SDG 675.919657
SEK 11.138733
SGD 1.440721
SHP 0.84812
SLE 27.733742
SLL 23563.779889
SOS 643.151938
SRD 42.470311
STD 23258.664553
STN 24.490554
SVC 9.847202
SYP 14610.562695
SZL 18.491868
THB 37.582744
TJS 10.3705
TMT 3.944245
TND 3.357305
TOP 2.70564
TRY 55.639483
TTD 7.640053
TWD 36.468653
TZS 2973.852994
UAH 50.478331
UGX 4648.2072
USD 1.123717
UYU 45.302527
UZS 13566.767338
VES 987.646423
VND 29098.079133
VUV 134.573156
WST 3.132678
XAF 655.957
XAG 0.019723
XAU 0.00026976363
XCD 3.036901
XCG 2.028218
XDR 0.794526
XOF 655.957
XPF 119.331742
YER 265.36608
ZAR 18.534623
ZMK 10114.801761
ZMW 22.53031
ZWL 361.836282
SSP 6470.487369
MXV 2.346356
  • BCC

    0.6500

    76.13

    +0.85%

  • GSK

    0.4900

    49.51

    +0.99%

  • RELX

    0.6400

    39.06

    +1.64%

  • RIO

    0.1100

    90.32

    +0.12%

  • RBGPF

    3.9200

    75.42

    +5.2%

  • NGG

    2.1500

    81.22

    +2.65%

  • BCE

    0.1500

    20.33

    +0.74%

  • RYCEF

    -0.3900

    17.61

    -2.21%

  • CMSD

    0.0100

    19.86

    +0.05%

  • BTI

    2.0000

    60

    +3.33%

  • VOD

    0.2600

    16.11

    +1.61%

  • AZN

    -1.2700

    165.41

    -0.77%

  • JRI

    0.0800

    10.56

    +0.76%

  • BP

    1.7700

    50.21

    +3.53%

  • CMSC

    0.0100

    19.89

    +0.05%


Venezuela and the Qatar Fund


A bank account in Qatar became the first holding point for $500 million in Venezuelan oil proceeds after Washington took control of the country’s crude exports in January 2026. The arrangement placed a vital source of national income under American supervision, far from Caracas. Although the payment route subsequently shifted to accounts managed by the US Treasury, questions about how the money is controlled and spent have followed it.

The chronology matters. Qatar’s involvement became public in January, following the US military operation that captured Nicolás Maduro on 3 January and the emergence of an interim government led by Delcy Rodríguez. By late February, Energy Secretary Chris Wright was explicitly stating that new oil proceeds were going directly into Treasury-managed accounts. Presenting the Qatari arrangement as a sudden discovery in October would obscure the development that now deserves scrutiny: the persistence of demands for an independently verifiable account of Venezuela’s oil income.

The first transactions were intended to turn Venezuelan crude into money that could sustain basic government operations. On 28 January, Secretary of State Marco Rubio told senators that $300 million of the initial $500 million had been transferred to Venezuela, while $200 million remained in the temporary Qatari account. He described a process in which Venezuelan authorities submitted monthly spending requests for American approval. Public-sector payroll was among the stated purposes of the disbursements.

In early February, the administration said the remaining $200 million had also been returned, completing the transfer of the initial proceeds. On 27 February, Wright confirmed that the revenue stream had been redirected to accounts handled by the Treasury. Those statements establish the administration’s account of the transfers. A full reconciliation would also identify the receiving accounts, subsequent payments and final beneficiaries.

Qatar’s role arose from the difficulty of moving Venezuelan money through a financial system shaped by sanctions and creditor claims. Venezuela faces obligations to bondholders, companies pursuing compensation for expropriated assets and other creditors. Oil receipts entering an accessible jurisdiction could become the subject of litigation. The administration presented the offshore account as a temporary way to move funds while reducing their exposure to seizure.

There is an economic rationale for preserving some export revenue during a national recovery. If incoming funds are immediately absorbed by competing claims, the government may struggle to pay employees or maintain essential services. But protection from creditors also changes who can enforce their rights and when. An arrangement designed to preserve operating cash therefore requires clear rules governing its duration, permitted uses and eventual relationship with a broader debt settlement.

The central distinction is between ownership of the money and authority to release it. President Donald Trump’s executive order of 9 January declared the designated funds to be Venezuelan government property, held by the United States in a custodial capacity. It sought to protect those funds from judicial attachment and placed decisions about their disposition under the secretary of state. The order’s own framework therefore recognises Venezuela’s ownership while assigning Washington substantial control over access.

That separation has political consequences. A government dependent on externally approved disbursements has less freedom to set its own spending priorities. Washington can argue that supervision helps ensure money reaches legitimate public purposes. For Caracas, the same mechanism makes the financing of ordinary administration contingent on decisions taken abroad. The resulting dependence extends well beyond the commercial terms of an individual oil sale.

Inside Venezuela, the practical importance of these receipts is immediate. The initial distribution plan envisaged $300 million reaching four domestic banks, enabling businesses to purchase dollars for imports of raw materials. In an economy short of foreign currency, access to export earnings affects whether companies can replenish supplies and sustain production. The economic effect depends on the timing and terms of dollar allocations, as well as the amounts announced.

This also complicates claims about how much money has reached the population. A payment to a government account, a dollar allocation to a commercial bank and a completed purchase of medical equipment describe different stages of expenditure. Establishing a public benefit requires following the transaction through those stages. An aggregate transfer figure alone cannot show whether a hospital received supplies or a worker received a salary.

By September, congressional scrutiny concerned sums far larger than the original Qatari deposit. On 17 September, Democratic senators Ron Wyden, Elizabeth Warren and Sheldon Whitehouse cited an estimate that at least $13 billion had been deposited in accounts overseen by the Treasury and State departments. They sought explanations of the safeguards against misuse and the authority governing disbursements. That estimate concerned cumulative receipts under the wider arrangement; determining the balance still held would require a reconciliation of deposits and withdrawals.

The dispute remained active in early October. On 2 October, Democratic members of the House Foreign Affairs Committee acknowledged receiving one document relating to a separate Venezuelan oil agreement, while maintaining that the disclosure fell well short of their requests. They again sought independent KPMG audits of the Foreign Government Deposit Funds and other outstanding records. The same statement described the Government Accountability Office’s examination as ongoing. These were specific demands for records, rather than a completed audit establishing where every dollar had gone.

Congressional allegations of possible misuse must be distinguished from findings of misconduct. The existence of an offshore account does not establish theft, and an incomplete public record cannot identify an unlawful beneficiary. It does, however, limit the ability of legislators and Venezuelan citizens to assess the administration’s assurances. The appropriate test is whether the transaction records support the stated purposes of the fund and reconcile with the balances reported by the banks.

Moving the accounts from Qatar to the United States changed the location of custody. It did not, by itself, answer the questions about oversight. Those questions include the price received for each cargo, the fees deducted, the amount credited to the fund and the basis for each authorised payment. An audit that covers only the arrival of money would leave the subsequent use of that money unresolved.

There is a further distinction between financial supervision and economic reconstruction. Reliable access to oil income can support purchases and public spending, but Venezuela’s recovery also depends on investment in production facilities and infrastructure. Companies considering long-term commitments need confidence in contracts and payment arrangements. Protecting current receipts while leaving future financial rules uncertain risks preserving an emergency mechanism without creating a durable basis for investment.

Qatar remains significant because it reveals how the arrangement began: Venezuelan exports generated revenue that was held in a third country and released under American supervision. The subsequent transfer of custody makes the underlying issue clearer. Venezuela’s recovery depends in part on whether control over those proceeds produces spending that its citizens can verify. A credible account must connect the oil sold to the money received, and the money received to the services and investment actually delivered.
Featured


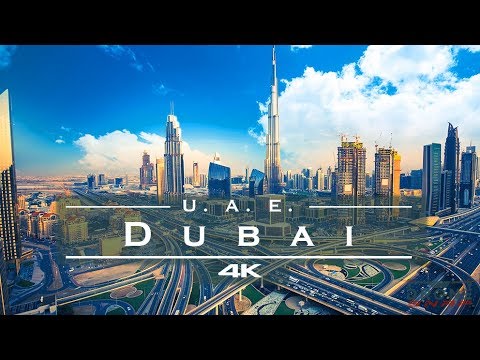
Marhabaan, welcome to the UAE and Dubai!

Marhabaan, welcome to the UAE and Dubai! The "skyward striving" Dubai next to ancient desert cities. Mysterious Bedouins and magnificent mosques exist peacefully alongside futuristic cities. Discover wadis and oases, golden sandy deserts, paradisiacal beaches and Arabian hospitality. The modern and the ancient Orient united in a book for dreaming.On this journey to Dubai and Abu Dhabi in the United Arab Emirates, the fairy tales of 1001 Arabian Nights meet the modern Arab world. These cascading cities enchant with their sky-high skyscrapers, fragrant souks, huge shopping centres and the ancient cultural heritage of the sheikhs.You can choose to stay in 4- or 5-star hotels with breakfast and swimming pools. You also have more options to book excursions so you can feel the magic of the East even more. If you want to do something out of the ordinary, you can spend an extra night in an enchanting hotel in the middle of the emirate's desert. Experience your own fairytale from 1001 nights and look forward to a holiday with plenty of casual extravagance in two superlative desert cities!

Trade and business at the Dubai Gold Souk

If Naif Deira is associated with a specific context, organization, or field, providing more details could help me offer more relevant information. Keep in mind that privacy considerations and ethical guidelines limit the amount of information available about private individuals, especially those who are not public figures. The Dubai Gold Souk is one of the most famous gold markets in the world and is located in the heart of Dubai's commercial business district in Deira. It's a traditional market where you can find a wide variety of gold, silver, and precious stone jewelry. The Gold Souk is known for its extensive selection of jewelry, including rings, bracelets, necklaces, and earrings, often crafted with intricate designs.Variety: The Gold Souk offers a vast array of jewelry designs, with a focus on gold. You can find items ranging from traditional to modern styles.Competitive Pricing: The market is known for its competitive pricing, and bargaining is a common practice. Prices are typically based on the weight of the gold and the craftsmanship involved.Gold and More: While gold is the primary focus, the souk also offers other precious metals such as silver and platinum, as well as a selection of gemstones.Cultural Experience: Visiting the Gold Souk provides not only a shopping experience but also a glimpse into the traditional trading culture of Dubai. The vibrant market is a popular destination for both tourists and locals.Security: The market is generally safe, and there are numerous shops with security measures in place. However, as with any crowded area, it's advisable to take standard precautions regarding personal belongings.Gold Souk is just one part of the larger Deira Souk complex, which also includes the Spice Souk and the Textile Souk. It's a must-visit for those interested in jewelry, and it reflects the rich cultural and trading history of Dubai.

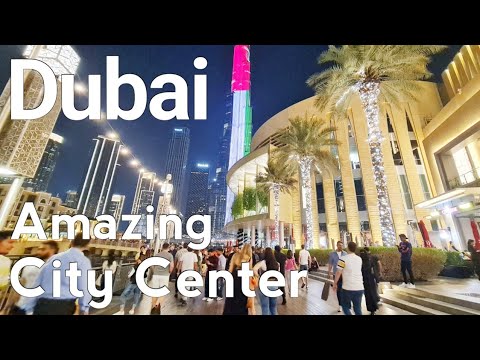
Dubai: Amazing City Center, Night Walking Tour

During this excursion, we leisurely explore Dubai Downtown and Burj Khalifa in the evening, giving you the chance to witness the captivating transformation of the district as it comes alive with the vibrant glow of thousands of lights. As the sun sets, the illuminated facade of Burj Khalifa and the enchanting Dubai Fountain collaborate to produce a genuinely magical atmosphere.Dubai Downtown, also known as Downtown Dubai, is a distinguished and iconic district situated in the heart of Dubai, United Arab Emirates. It is a renowned neighborhood celebrated for its striking architecture, luxurious living, and exceptional entertainment options. At the core of Downtown Dubai stands the Burj Khalifa, a towering skyscraper that holds the title of the world's tallest man-made structure and serves as an emblem of modern Dubai.Burj Khalifa: The focal point of Downtown Dubai, Burj Khalifa, is famous for its groundbreaking height, reaching an impressive 828 meters (2,722 feet). Designed by architect Adrian Smith, its distinctive Y-shaped design encompasses a mix of residential, commercial, and hotel spaces.Dubai Mall: Adjacent to Burj Khalifa is the Dubai Mall, one of the largest shopping malls globally, featuring an extensive array of retail outlets, from high-end boutiques to international brands. The mall also provides various dining options, and entertainment attractions like an indoor ice rink and an aquarium, and hosts the mesmerizing Dubai Fountain.Dubai Fountain: Located just outside the Dubai Mall, the Dubai Fountain is a captivating attraction that presents a nightly spectacle of water, music, and light, captivating visitors with its perfectly synchronized performances.Emaar Boulevard: Stretching through Downtown Dubai, this boulevard is adorned with restaurants, cafes, and shops, making it a popular spot for leisurely strolls, dining, and people-watching.Luxury Living: Downtown Dubai boasts numerous upscale residential buildings and hotels, making it an appealing locale for those seeking a sophisticated urban lifestyle.Cultural Attractions: The Dubai Opera, an iconic cultural venue within the district, hosts a diverse range of performances, including opera, ballet, concerts, and theater productions.Transportation: Downtown Dubai is well-connected through public transportation, including the Dubai Metro, facilitating easy access to other parts of the city.In summary, Downtown Dubai is a dynamic and vibrant district that stands as a testament to Dubai's modernity and grandeur. It seamlessly combines architectural wonders with shopping, entertainment, and cultural offerings, creating a truly extraordinary destination.